Mortgage rates ease to 7.11%—what the change means for a payment
A $400,000 loan illustrates the small weekly improvement and the larger gap from a year ago.
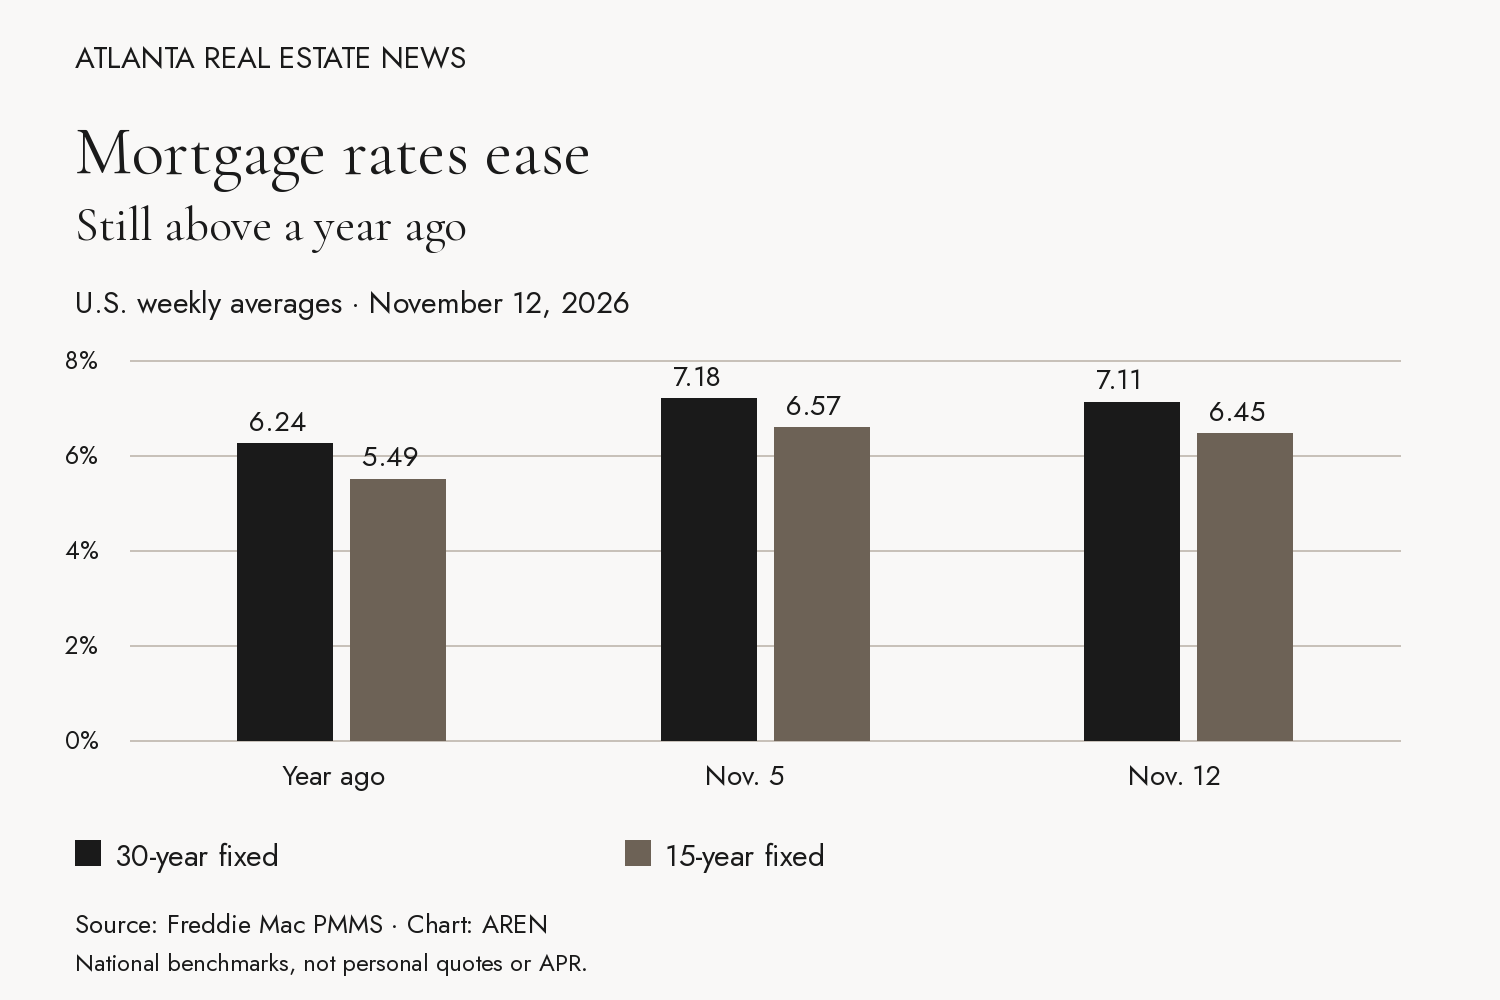
Photo creditDetails
A weekly decline, with a higher annual comparison
Freddie Mac’s November 12 survey puts the average 30-year fixed mortgage rate at 7.11%, down from 7.18% a week earlier. The 15-year average fell to 6.45% from 6.57%. Both remain above the comparable year-ago readings of 6.24% and 5.49%.
The national figures give Atlanta buyers a financing benchmark rather than a local lender quote. They describe conventional conforming purchase applications and should not be treated as an advertised APR or a rate available to every borrower.
What seven basis points changes on a payment
For an illustrative $400,000 loan repaid over 30 years, principal and interest would be approximately $2,710 a month at 7.18% and $2,691 at 7.11%. That is about $19 less per month with the same balance and repayment term.
At 6.24%, the comparable payment would be about $2,460—roughly $231 below the payment at this week’s benchmark. The contrast explains why a weekly improvement does not necessarily restore last year’s purchasing budget.
AREN calculated these figures using a fixed-rate amortization formula with 360 monthly payments, rounding the results to the nearest dollar. They exclude property taxes, homeowners insurance, mortgage insurance, association charges, fees and points. They are examples, not financing offers.
Compare the complete offer
The Consumer Financial Protection Bureau recommends comparing Loan Estimates for the same loan amount and type. Look beyond the interest rate to principal and interest, mortgage insurance, total monthly payment, upfront loan costs, lender credits and cash needed at closing.
Timing matters: the CFPB notes that rates can change daily, so estimates produced on different days may reflect different market conditions. A lower estimate for taxes or insurance also does not establish that one lender is cheaper; those costs are outside the lender’s control.
The standardized Loan Estimate describes expected terms, costs and features after an application. Receiving it does not mean the lender has approved or denied the loan, according to the CFPB.
Putting the comparison to work in Atlanta
For a buyer evaluating a specific property, the useful next calculation is the full monthly cost at an actual quoted rate. Keeping the property, down payment and term constant makes the effect of financing easier to see. Changing several assumptions at once can obscure whether a lower payment comes from a cheaper loan, a larger cash contribution or a longer repayment period.
AREN’s Data Desk now carries the November 12 benchmark alongside separately dated local market figures. The rate release does not update Atlanta sale prices or establish how a particular neighborhood’s market has changed.
Sources & further reading
Sources checked 2026-11-12.
About Atlanta Real Estate News
Atlanta Real Estate News is an independent publication covering property, development, business, design and life in Metro Atlanta. We exist to help readers understand what is changing, why it matters and what to watch next through clear reporting, verified sources and local perspective.